The Car Was Gone by Morning: How One Family’s Dream Purchase Became a Community’s Wake-Up Call
A single mother’s hard-earned savings vanished in a single tow truck hook—now her neighbors are asking the question every American should fear: who really owns the car in your driveway?
The keys felt warm in her hand. The paperwork looked official. The seller smiled, shook her hand, and drove off in a friend’s car. For one brief, shining moment, a working mother of two believed she had finally caught a break.
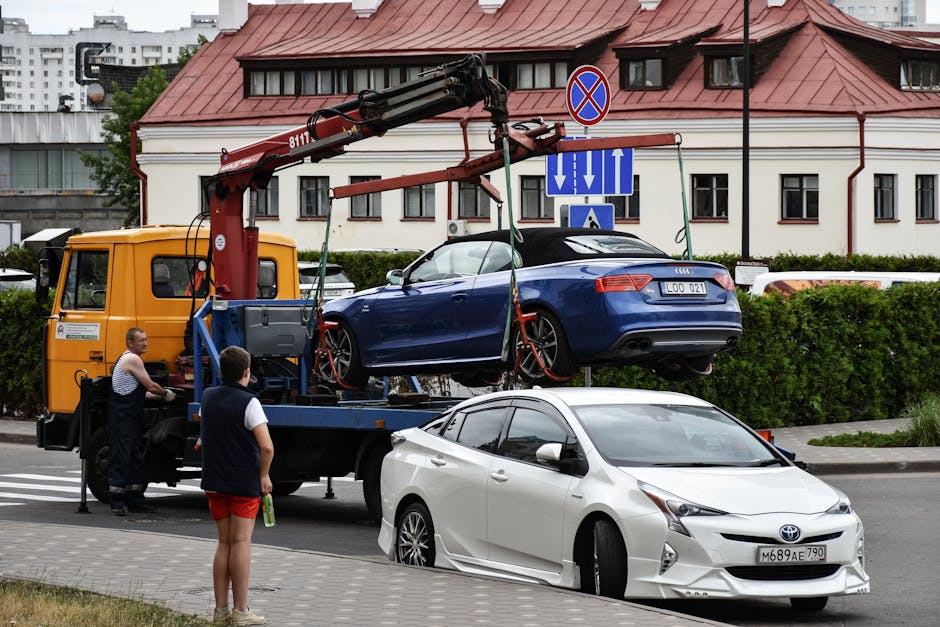
By sunrise the next day, that break was gone. A tow truck was idling in her driveway, and a stranger with a clipboard was explaining that the vehicle she had just paid for in full did not legally belong to her.
She stood on her porch in her bathrobe, coffee going cold, watching her family’s only reliable transportation disappear down the street. The money was already spent. The seller’s phone was already off.
The Legal Precedent: Where Private Sales and State Title Codes Collide
What happened to this family is not a freak accident. It is a predictable outcome of a legal gap that swallows thousands of American buyers every year.
When a private seller hands over a vehicle without a clean, transferable title, the buyer receives no legal ownership—only possession. And possession, under state motor vehicle codes, is nothing more than a temporary loan from the rightful owner.
The real owner—often a lender, a dealership, or a prior titleholder—retains every legal right to reclaim the vehicle. The buyer, meanwhile, is left holding a worthless bill of sale and a phone number that no longer works.
Legal aid attorneys describe these cases as heartbreaking and nearly unwinnable. The buyer’s only path to recovery is a civil suit against the seller—a person who has already demonstrated a willingness to disappear.
“She did everything a reasonable person would do. She checked the VIN, she got a receipt, she paid in cash. None of that matters if the title never gets transferred. The law doesn’t care about good faith—it cares about paperwork.”
For this family, the paperwork was never going to be enough. And the people who sold them that car knew it.
- Did the seller knowingly transfer a vehicle they did not legally own, opening the door to civil fraud claims?
- Why did the state motor vehicle database not flag the title discrepancy before the sale was completed?
- What legal remedies exist for buyers who lose both the vehicle and their money in a private transaction?
- Should states require title verification at the point of sale to prevent these losses?

Civil Liability and Consumer Protection: The Hidden Risks of Private Vehicle Sales
The used car market is the Wild West of American commerce. Unlike licensed dealerships, private sellers face almost no regulatory oversight—no bonding requirements, no mandatory title disclosures, no cooling-off periods.
Consumer protection laws vary wildly from state to state. Some states require sellers to disclose known title defects. Others require nothing more than a handshake and a bill of sale.
For buyers, the burden of due diligence falls entirely on their shoulders. And even the most careful buyer can be fooled by a forged title, a washed VIN, or a seller who simply lies.
Attorneys who handle these cases say the same thing repeatedly: the system is designed to protect the titleholder, not the buyer. And when the titleholder is a bank or a prior owner who never authorized the sale, the buyer has no seat at the table.
The family in this case is now navigating a maze of small claims court, consumer complaint filings, and calls to a state attorney general’s office that has thousands of similar cases pending.
Similar civil confrontations across the country are forcing community leaders and local venues to confront serious liability under state regulations. Explore the full legal breakdown of related incidents →
But here is what makes this story different. What makes it worth telling.
The neighbors saw what happened. They watched the tow truck. They saw the mother standing on her porch, phone in hand, trying to explain to someone on the other end of the line that she had done nothing wrong.
Within hours, a GoFundMe appeared. A local mechanic offered to inspect any vehicle for free before purchase. A retired paralegal started a Saturday morning clinic at the community center to teach people how to verify titles before handing over cash.
“We couldn’t get her car back. But we could make sure it never happens to another family on this block. That’s what neighbors do.”
Constitutional Boundaries and the Enforcement of Public Accommodation in Private Sales
Legal experts point to a frustrating reality: private vehicle sales occupy a gray zone where constitutional protections for consumers are weakest.
Public accommodation laws, which protect buyers in commercial transactions, rarely extend to individual-to-individual sales. The result is a two-tiered system where the same transaction is protected at a dealership but virtually unprotected in a driveway.
Some state legislators have introduced bills requiring title verification at the point of sale. Others have proposed mandatory disclosure forms. None of these measures have gained widespread traction.
Meanwhile, families like this one are left to navigate a system that assumes they knew the risks—even when no one ever told them what those risks were.
The mother has not recovered her money. The seller has not been located. The tow company followed the law. The bank that held the title followed the law. Everyone followed the law except the person who took her money and disappeared.
And that, according to every attorney who reviewed this case, is exactly how the system is designed to work.
If you are buying a car from a private seller tomorrow, ask yourself one question before you hand over a single dollar: whose name is actually on that title? Because if the answer is not the person standing in front of you, the car in your driveway is not yours.
It never was.