The Hidden Financial Liability Traps Draining American Savings: How Private Property Ordinances Are Quietly Bankrupting Ordinary Citizens
Inside the high-stakes legal battle between local business owners and private security contractors—and the terrifying financial fallout awaiting homeowners who don’t know their rights.
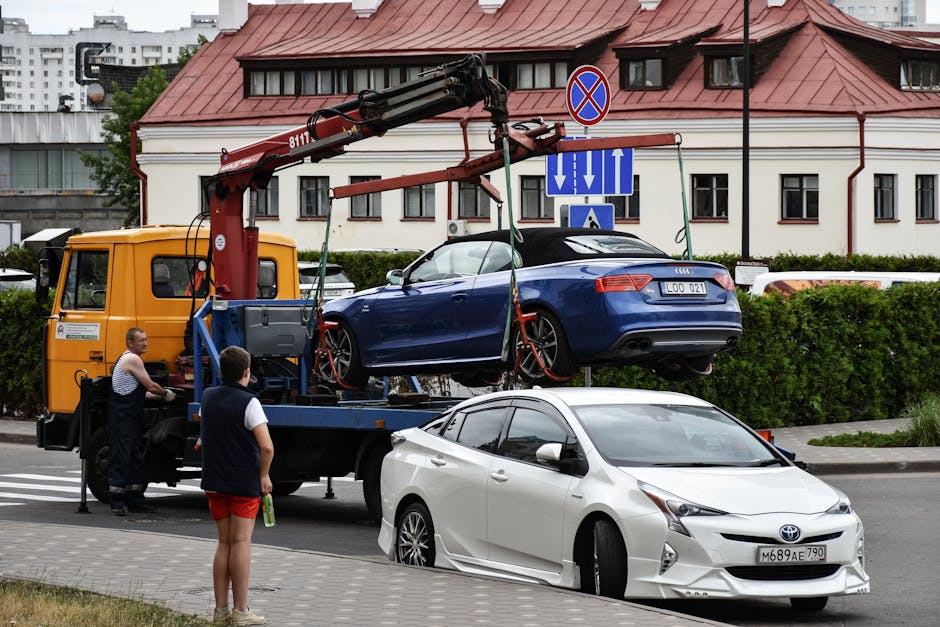
Imagine pulling into a nearly empty commercial lot for a five-minute errand, only to return and find your vehicle gone. No warning. No ticket on the windshield. Just an empty space and a sinking feeling in your stomach. Within hours, that brief stop transforms into a financial nightmare involving impound fees, administrative charges, and a legal fight you never asked for. This is the reality facing thousands of Americans every single day, and the financial consequences are devastating.
The scene playing out across the country is remarkably consistent. Private property owners, frustrated by unauthorized use of their lots, are increasingly turning to aggressive enforcement tactics. Third-party towing companies patrol these lots like predatory lenders, waiting for the slightest violation to swoop in and extract maximum profit from unsuspecting drivers.
What most Americans don’t realize is that these private enforcement operations exist in a shadowy legal gray zone. The contracts between property owners and towing companies are private agreements. But the enforcement of those agreements intersects with state civil codes, consumer protection statutes, and constitutional guarantees that most people never think about until they’re the one staring at a four-figure bill.
The Legal Precedent: Where Private Rules Clash With State Civil Codes
The fundamental question that courts across the nation are grappling with is deceptively simple: Can a private property owner create and enforce rules that override state consumer protection laws? The answer, according to a growing body of case law, is far more complicated than most business owners want to admit.
State civil codes typically require specific signage, notice provisions, and grace periods before a vehicle can be legally removed from private property. These aren’t suggestions—they’re statutory requirements. When property owners or their agents skip these steps, they open themselves up to significant legal liability.
Consumer protection attorneys report a dramatic increase in cases involving improper vehicle removal from commercial lots. The pattern is always the same: aggressive enforcement, minimal notice, maximum fees. And the victims are almost always ordinary working Americans who can least afford the financial hit.
The financial liability doesn’t stop at the impound fee. Victims report losing wages from missed work, paying for rideshare services to retrieve their vehicles, and facing unexpected childcare costs. These cascading expenses can quickly exceed a thousand dollars for a single incident.

- Do property owners have unlimited authority to remove vehicles, or do state civil codes impose mandatory notice requirements that most businesses ignore?
- When private enforcement agents violate consumer protection statutes, what financial liability do they face—and why do so few victims pursue claims?
- How do insurance companies handle claims arising from wrongful vehicle removal, and are policyholders unknowingly waiving their rights?
Civil Liability & Business Codes: Hidden Legal Risks for Local Venues
Business owners who contract with aggressive enforcement companies often believe they’re protected by indemnification clauses. These contractual provisions supposedly shift all liability to the towing company. But legal experts warn that these protections are far from bulletproof.
When a business invites the public onto its property for commercial purposes, it assumes certain legal obligations. Courts have consistently held that businesses cannot simply outsource their duty of care to third-party contractors and wash their hands of responsibility.
“The indemnification clause is only as good as the paper it’s printed on. When a consumer’s rights are violated, courts look at the actual conduct, not the contract language. And juries are not sympathetic to businesses that prey on their own customers.”
The financial exposure for local venues is substantial. Beyond actual damages, prevailing consumers can recover statutory penalties, attorney fees, and in some jurisdictions, punitive damages for egregious conduct. For a small business operating on thin margins, a single lawsuit can be existential.
Insurance carriers are also taking notice. Commercial liability policies increasingly include exclusions for intentional torts and statutory violations. This means business owners may find themselves personally on the hook for judgments their insurance won’t cover.
Similar civil confrontations across the country are forcing community leaders and local venues to confront serious liability under state regulations. Explore the full legal breakdown of related incidents →
Consumer Protection & Financial Fallout: What Precedent Does This Set?
The stakes extend far beyond individual disputes. Every time a consumer successfully challenges an improper vehicle removal, they establish precedent that protects others. Conversely, every victim who pays the fee and walks away without fighting back emboldens bad actors to continue their predatory practices.
Consumer rights advocates emphasize that most Americans are woefully uninformed about their legal options. State attorney general offices report that complaints about private towing and vehicle removal have increased dramatically, yet formal legal actions remain relatively rare.
The reason is simple economics. Pursuing a claim requires time, legal knowledge, and often upfront costs that many victims cannot afford. The system effectively rewards those who exploit this information asymmetry.

Financial recovery is possible, but only for those who understand the process. Documenting everything, preserving evidence, and consulting with consumer protection attorneys can transform a seemingly hopeless situation into a successful claim. The key is acting quickly and refusing to accept the narrative that private property rules are absolute.
The legal landscape is shifting. Courts are increasingly skeptical of aggressive private enforcement tactics. State legislatures are considering new consumer protection measures. But for now, the burden falls on individual Americans to know their rights and fight back against financial exploitation.
The next truck that pulls into your parking spot might not be delivering goods. It might be there to take your vehicle and your money. And the only thing standing between you and financial devastation is the knowledge that private property rights have limits—and that those limits are enforceable in a court of law.
But here’s what the property owners and their enforcement agents won’t tell you: the statute of limitations on many consumer protection claims is shockingly short. Miss the window, and your rights evaporate. The clock starts ticking the moment the hook touches your bumper.