The Hidden Legal Loopholes That Could Wipe Out Your Savings: What a 70-Year-Old’s Civil Dispute Reveals About Financial Liability
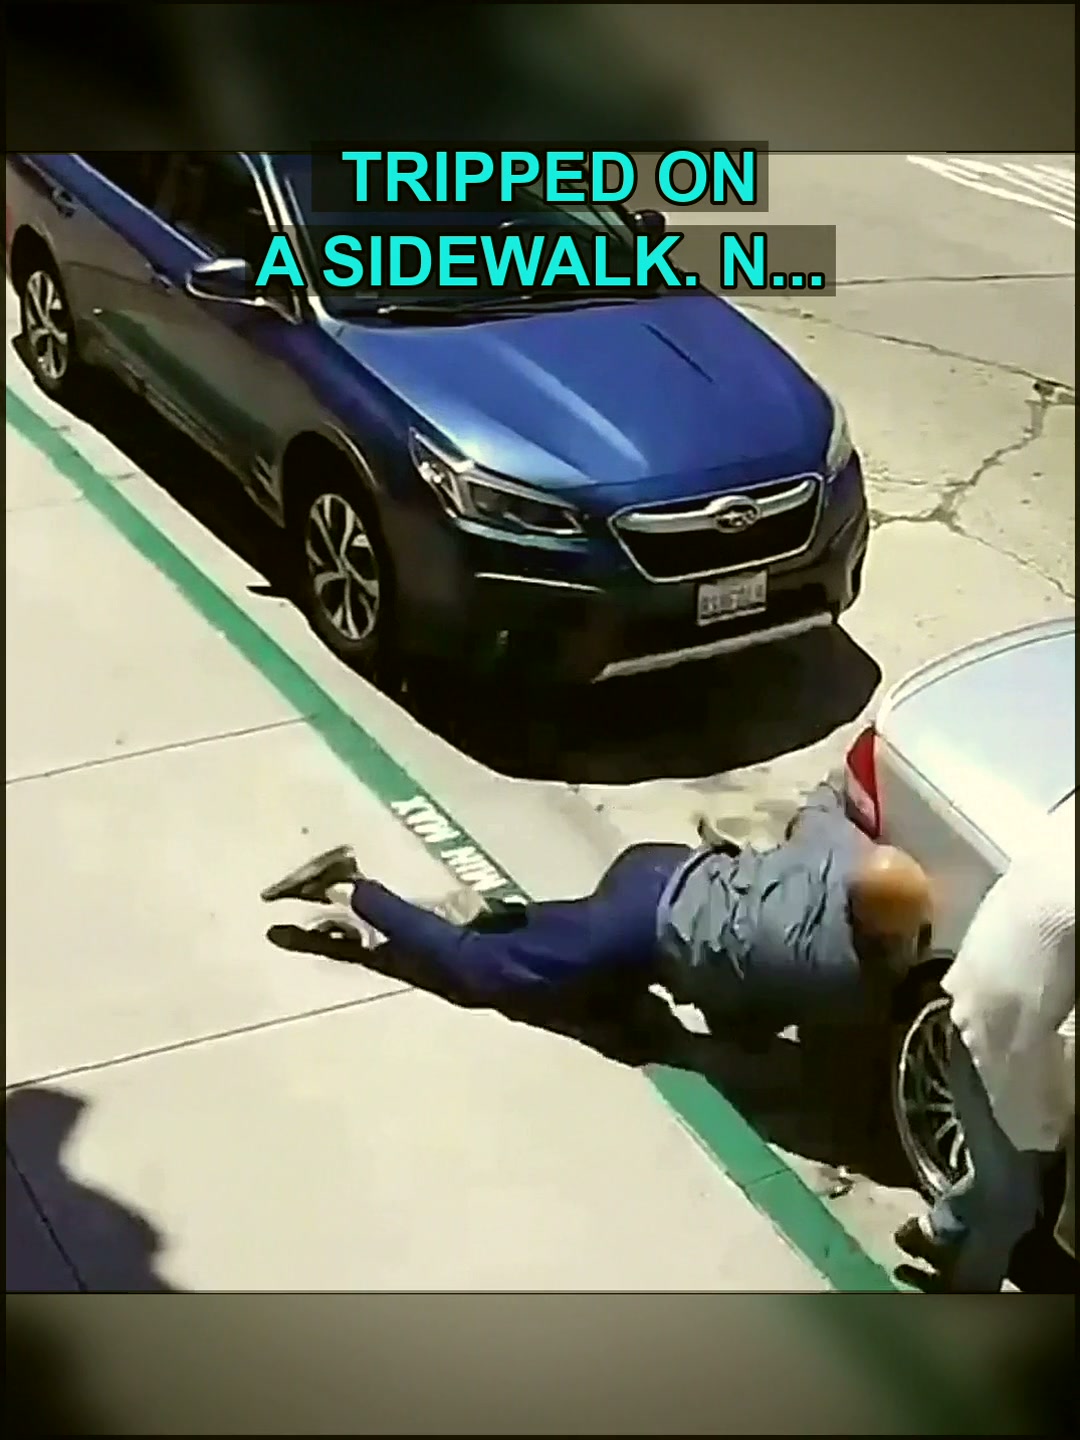
When a routine encounter spirals into a legal and financial nightmare, the consequences expose how little most Americans actually know about their rights, their coverage, and the true cost of accountability.
Imagine pulling into a spot you have used a hundred times before, only to find yourself staring down a legal claim that could drain your retirement account. That is the reality one 70-year-old woman is reportedly facing after what began as an ordinary day turned into a full-blown civil dispute. The details are still emerging, but the financial stakes are already terrifying.
This is not a story about a single bad afternoon. It is a story about a system that quietly transfers risk onto ordinary people, then charges them thousands to navigate the fallout. And for seniors living on fixed incomes, the margin between stability and financial ruin is razor-thin.

The Legal Precedent: Where Private Rules Clash With State Civil Codes
Here is what most people never learn until it is too late: private property rules, homeowners association bylaws, and local ordinances do not automatically override state civil codes. When they conflict, the outcome depends on documentation, jurisdiction, and whether proper legal notice was given.
In disputes like the one involving the 70-year-old woman, the entire case can hinge on a single piece of paper, a witness statement, or a timestamped photograph. Without that evidence, the burden shifts unfairly onto the individual, not the entity making the claim.
“The average American has no idea how quickly a civil dispute can become a five-figure financial liability. Most people find out only after the demand letter arrives.”
Legal analysts who track consumer protection cases say the pattern is consistent: the party with better records and deeper pockets usually wins, regardless of who was actually right. That is not justice. That is a math problem.
- Does the individual’s homeowners or renters insurance policy actually cover civil claims of this nature, or will the insurer deny coverage citing a policy exclusion?
- What documentation standards do state civil codes require before a private party can pursue financial damages against a senior citizen?
- If the dispute escalates to small claims or civil court, who bears the burden of proof, and what happens when the accused cannot afford legal representation?
Civil Liability and Insurance Denials: The Hidden Financial Trap for Ordinary Americans
This is where the story gets worse. Even if you have insurance, there is no guarantee your provider will step in. Homeowners policies frequently exclude claims arising from business activities, intentional acts, or disputes classified as contractual rather than accidental.
That means a 70-year-old retiree could face a legal demand, file a claim with her insurer, and receive a denial letter citing a clause buried on page 34 of a policy she signed a decade ago. The insurer walks away. The senior is left holding the bill.
Consumer protection attorneys say the single most important thing any American can do is document everything. Photographs. Timestamps. Written communications. Witness names. Without that, you are relying on memory and goodwill, and neither holds up in court.
Similar civil confrontations across the country are forcing community leaders and local venues to confront serious liability under state regulations. Explore the full legal breakdown of related incidents →

Consumer Protection and Financial Fallout: What Precedent Does This Set for Your Rights?
The broader implications are staggering. If a 70-year-old woman can be dragged into a civil dispute over an everyday incident, so can you. The legal system does not care about your retirement timeline. It cares about evidence, jurisdiction, and whether the other side filed the right paperwork first.
Financial planners now advise clients to set aside an emergency legal fund separate from their savings. The recommendation is not paranoia. It is a direct response to a system where the cost of defending yourself can exceed the cost of the original claim by a factor of ten.
“Accountability in civil disputes is not about who is right. It is about who can prove it. And proving it costs money most Americans do not have set aside.”
For the 70-year-old at the center of this dispute, the final number has not been determined. But the damage is already done. Legal fees, insurance complications, and the emotional toll of fighting a system designed for corporations, not retirees.
The demand letter sits on the kitchen table. The insurance company has not called back. And somewhere in a file cabinet, a policy she has paid into for twenty years contains a single sentence that could change everything. She has not found it yet.