The School-Gate Nightmare No One Warns You About: Who Pays When the Crowd Turns on Your Family?
It starts as a routine pickup. It ends with your family surrounded, your phone recording, and your insurer quietly deciding whether you are on your own.
- Most homeowners and auto policies contain exclusions that can leave families exposed after a public confrontation.
- Documentation captured in the moment often decides whether an insurance claim or civil suit survives.
- Legal options exist for ordinary families, but the window to use them closes fast.
Imagine pulling up to your child’s school, engine still running, when a group forms around your vehicle. Your kids are in the back seat. Your phone is in your hand. And in that moment, you realize no one is coming to help you fast enough.
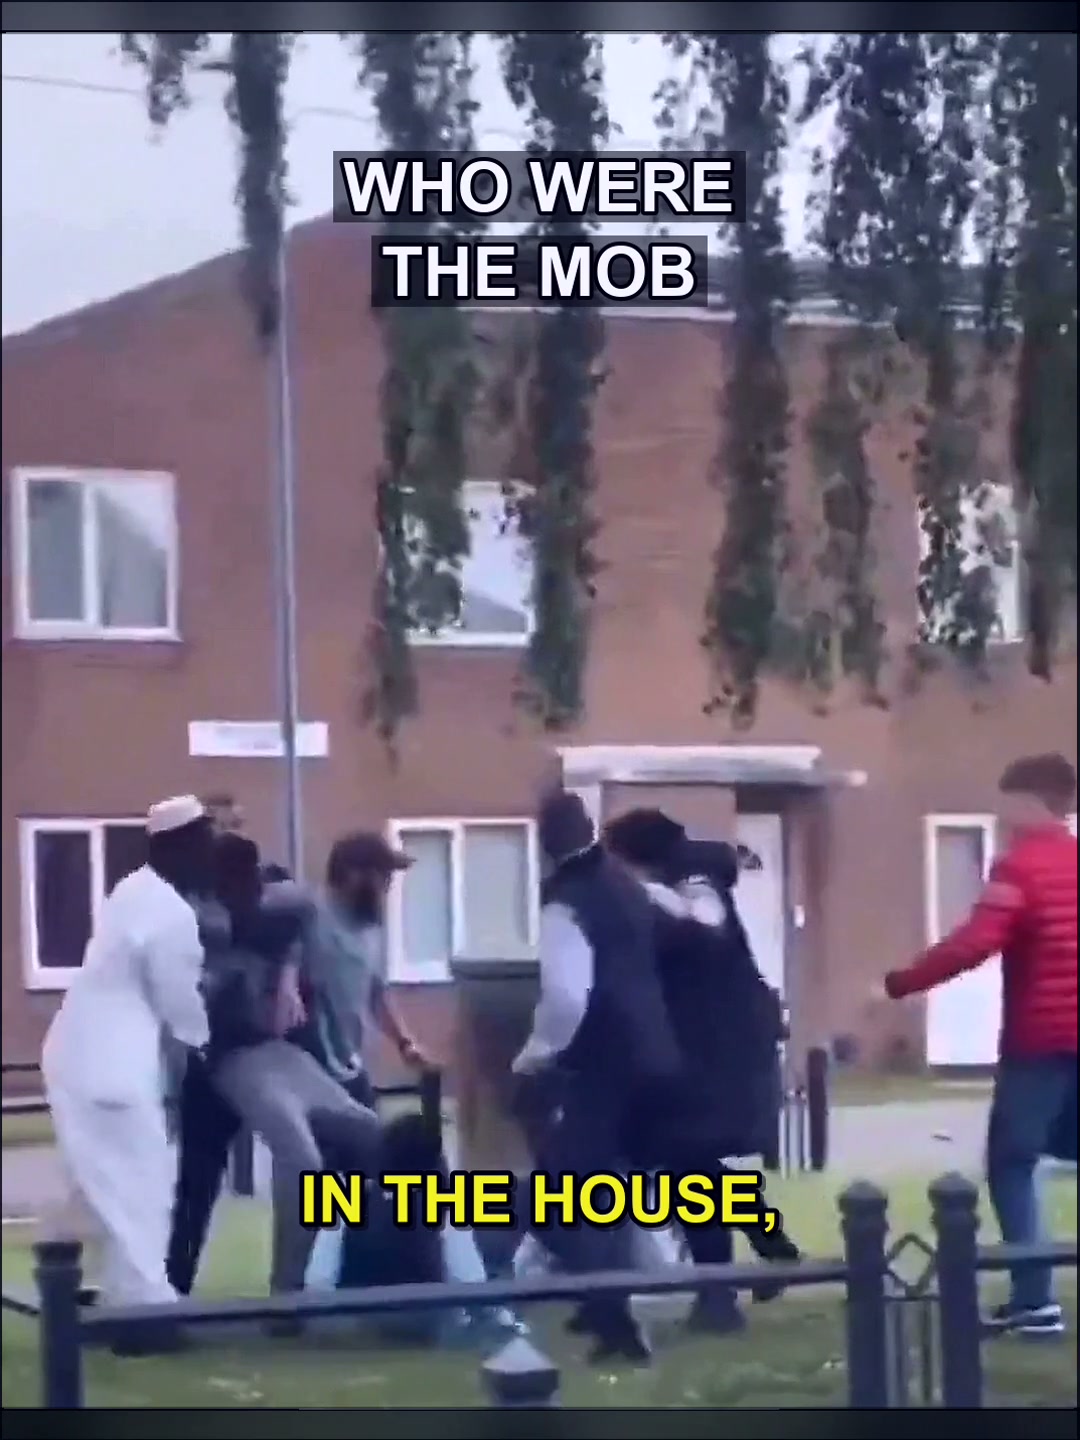
That is the scene reportedly described outside a primary school in England, where parents were allegedly surrounded by a crowd in an incident that has since spread across social media. The details remain disputed. The financial and legal fallout, however, follows a pattern American families would recognize instantly.
Because here is the part nobody explains at the school gate: when something goes wrong in public, the bill does not disappear. It lands on someone. And insurers have spent decades making sure it does not land on them.
The Insurance Trap Waiting in Your Glovebox
Most Americans assume their auto and homeowners policies cover “anything that happens.” That assumption is expensive.
Standard policies routinely exclude intentional acts, incidents arising from expected confrontations, and claims where the policyholder is deemed a willing participant. A family caught in a public dispute can discover their coverage evaporates precisely when they need it most.
Then comes the second punch. Even when coverage applies, the payout caps are often far below the real cost. Deductibles apply. Sub-limits apply. And the burden of proof lands squarely on the family that was already having the worst day of their year.
“The policy you bought is not the policy you think you bought. Read the exclusions before you need them, not after.”
The Documentation Rule That Decides Everything
Legal professionals repeat one instruction more than any other: record everything, immediately.
Video captured in the moment is not just evidence. It is leverage. It determines whether an insurer treats a claim as credible or contestable. It determines whether a civil filing moves forward or stalls. It determines whether a family recovers a fraction of their losses or absorbs all of them.
Families who wait, who assume someone else will handle it, who trust that the system will sort itself out, are the ones who end up paying. Not the crowd. Not the school. Not the insurer. Them.

The Legal Precedent Every Parent Should Understand
Courts on both sides of the Atlantic have consistently held that public entities and schools carry limited liability for incidents occurring on or near their grounds. Sovereign immunity doctrines, notice requirements, and short filing deadlines routinely shut out families who assumed the institution would step up.
That means the path to accountability usually runs through civil claims against individuals, not institutions. And civil claims require identification, evidence, and money to pursue.
The families who succeed are the ones who moved first. Who preserved footage. Who filed notices within days, not months. Who understood that the legal system rewards preparation and punishes hesitation.

What Ordinary Families Are Never Told
There is a quiet industry built on the gap between what people believe their coverage does and what it actually does. Adjusters are trained to find exclusions. Attorneys are trained to find liability. Families are left to find out the hard way.
The lesson from incidents like the one reported overseas is not about geography. It is about exposure. It is about the fact that any parent, in any country, in any pickup line, can end up in a situation where the only thing standing between their family and financial ruin is a phone full of footage and a lawyer who answers on the first ring.
Most people will read this and assume it will never happen to them.
That is exactly what the last family thought, right before the crowd formed.