The Hidden Medical Bill Crisis: What a Chicago Street Incident Reveals About Patient Rights and Out-of-Pocket Chaos
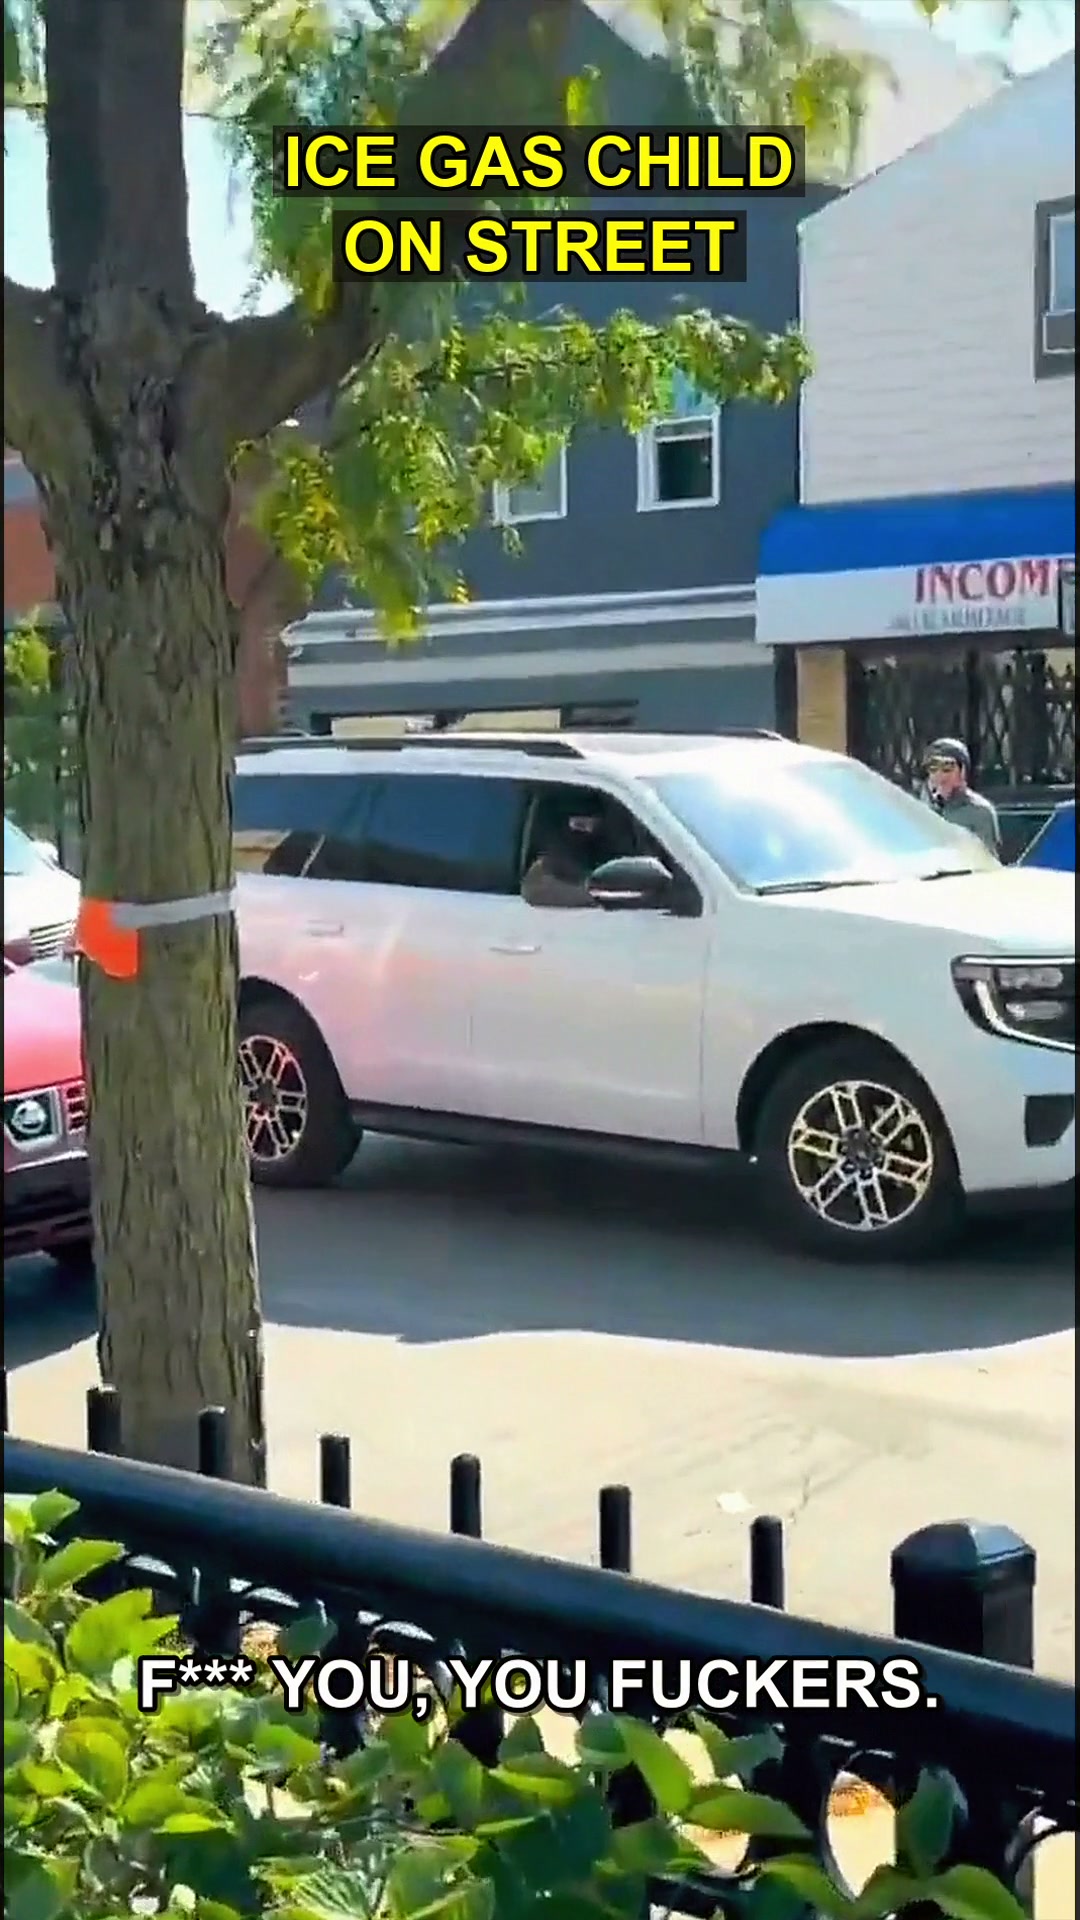
GENERAL CONTEXT ONLY.
When the air turns toxic on a random Tuesday, the medical debt doesn’t stop at the ambulance door. Here is what every family needs to know about insurance gaps and the fight for fair treatment costs.
- Chemical exposure on a public street is not just a physical health crisis; it is an immediate trigger for unexpected out-of-pocket medical expenses.
- Insurance claim denials for respiratory distress and chemical inhalation are rising, leaving ordinary families with staggering bills for ER visits and follow-up care.
- Knowing your patient rights regarding emergency care and air quality incidents can be the difference between financial ruin and manageable debt.
Picture this: you are walking your kid to school, the morning is crisp, and then suddenly the air turns thick with a burning chemical fog. Your lungs seize. Your toddler starts gasping. Within minutes, you are in an ambulance, watching your child struggle to breathe, with no idea what you just inhaled or who is going to pay for the oxygen mask.
That nightmare became a terrifying reality for families in Chicago this week. Reports confirm that a federal operation went sideways on a crowded public street, unleashing a chemical agent that sent a two-year-old to the ER and left adults vomiting on the sidewalk. A local elementary school slammed its doors, locking down recess as the toxic cloud drifted toward the playground.

But while the immediate danger is over, a second, quieter crisis is just beginning: the medical bills. The insurance claims. The denial letters. The out-of-pocket reality that hits families weeks after the coughing stops.
The Financial Fallout Nobody Talks About
When a chemical agent hits your respiratory system, the medical response is immediate, but the financial response is slow and brutal. An ambulance ride alone can rack up charges between $1,200 and $2,500 depending on the city and the level of care. For a child requiring oxygen therapy and observation, a standard ER visit can easily exceed $3,000 before a single diagnostic test is run.
Here is the unedited truth: most standard health insurance plans treat chemical inhalation exposure as a “respiratory condition,” which often requires pre-authorization for follow-up inhalers or nebulizer treatments. If the claim is coded incorrectly—and it often is—your insurance company will slap a denial on it faster than you can say “appeal.”
In this specific case, parents are now left with a terrifying question: if the air was deemed unsafe for recess, why is the financial burden of proving that falling on the victims? The elementary school lockdown proves the severity. The hospital visit proves the physical damage. But the insurance companies are already sharpening their pencils to argue that the treatment was “not medically necessary” because the symptoms—coughing, wheezing, vomiting—could be “attributed to a common virus.”
It is incredibly frustrating to see families caught in this bureaucratic crossfire, where the system designed to help them instead demands they prove their child’s breathing trouble is real.
“They watched our kids choke on the sidewalk, and the first piece of mail we will get from the hospital will be a bill for the privilege of being poisoned.” — A parent on the scene, visibly shaken.
The Patient Advocacy Trap
Common sense says that if a government operation causes a medical emergency, the government pays. But common sense and the healthcare billing system rarely speak the same language. In reality, the burden of filing a claim against a federal agency for “toxic tort” exposure is so labyrinthine that most families give up after the first 90 days of paperwork.
What are the actual options? First, you must demand an itemized bill from the hospital. Second, you must request a “letter of medical necessity” from the attending physician specifically linking the respiratory distress to the chemical agent. Third, you must file a claim with the Federal Tort Claims Act (FTCA) if a federal employee was involved—a process that has a strict two-year statute of limitations and requires a formal administrative claim before any lawsuit can be filed.

But here is the catch that will make your blood boil: the FTCA does not cover “discretionary functions.” If the agency argues that the decision to deploy the chemical agent was a discretionary act of policy, they are immune. You are left holding the bill for the ambulance, the ER copay, and the follow-up pediatric pulmonologist—all while your child is still coughing.
The Legal Precedent
This is not a hypothetical fear. Legal experts point to a pattern where local authorities are rarely held financially accountable for chemical incidents that drift into civilian populations. The doctrine of “qualified immunity” shields individual officers from lawsuits, and the “discretionary function exception” shields the agency from paying damages. The result is a perfect storm of accountability avoidance.
For the parents in Chicago, the immediate priority is the health of their two-year-old. But the secondary priority—the medical debt—is about to become a permanent fixture in their lives. They will receive a bill for the ER visit. They will receive a separate bill from the ambulance company. They will receive a bill from the hospital for the “observation” hours. And when they try to submit these to their insurance, they will likely face a denial because the claim form asks for a “diagnosis code” that does not neatly fit “exposure to law enforcement chemical agents.”
Accountability is not just about who pressed the button on the canister. It is about who presses the button on the payment terminal at the pharmacy. Right now, that button is being pressed by the parents—and they are the ones who will be paying for this for years to come.
So here is the sobering reality: the chemical fog may have lifted, but the financial fog is just rolling in. And unlike the traffic that allegedly triggered this mess, there is no clear lane to escape the consequences. The bills are coming. The question is whether anyone in a position of power will have the decency to answer for them—or whether the family will be left to fight the insurance machine alone, one denied claim at a time.