Inside the Quiet Crisis Reshaping Senior Financial Protection and Community Trust
As elder fraud cases climb nationwide, families are discovering that the safeguards meant to protect retirement savings are failing the very people they were designed to shield
Imagine checking your mother’s bank account on a Tuesday morning and discovering that $47,000 has vanished over six weeks. Not stolen in a dramatic heist. Drained through a series of small, authorized-looking transactions that she approved herself, believing she was protecting her family.
This scenario plays out thousands of times every day across the United States. The victims are not confused or incompetent. They are sharp, independent seniors who built their retirement through decades of discipline. And they are being systematically targeted by operations that understand exactly how to exploit the systems meant to protect them.
The numbers are staggering in their cruelty. According to federal data, reported elder fraud losses have increased by more than 300 percent over the past five years. But experts agree the real figure is far higher. Shame keeps most victims silent. Families stay quiet to protect their loved one’s dignity. And the perpetrators count on that silence.

The Legal Precedent: Where Private Financial Rules Clash With State Elder Protection Codes
Here is where the story takes a darker turn. When a senior’s retirement account is drained through what banks classify as “authorized transactions,” the legal system often treats the case as a voluntary transfer rather than fraud. The victim signed the paperwork. The victim authorized the wire. Case closed.
But elder law attorneys argue this framework was built for a world that no longer exists. Modern fraud operations use psychological manipulation so sophisticated that the transactions appear completely legitimate on paper. The senior genuinely believes they are acting in their own interest.
State elder protection codes vary wildly in how they handle these cases. Some states require financial institutions to report suspected exploitation within 24 hours. Others have no mandatory reporting requirement at all. This patchwork of regulations creates a system where a senior in one state receives protection that a senior in a neighboring state can only dream about.
- Why do financial institutions classify manipulated transactions as “authorized” when the senior lacked full understanding of the consequences?
- What liability do banks carry when they fail to flag unusual withdrawal patterns from accounts belonging to seniors over 70?
- How can families pursue civil remedies when the legal system treats exploitation as a voluntary financial decision?
The financial stakes extend far beyond the immediate loss. When a senior’s retirement account is depleted, the burden shifts to family members who may lack the resources to provide equivalent care. Medicare and Social Security benefits do not replenish what was taken. The damage cascades through generations.
“The system was designed to protect competent adults from government overreach. It was never designed to protect them from predators who weaponize that independence against them.”
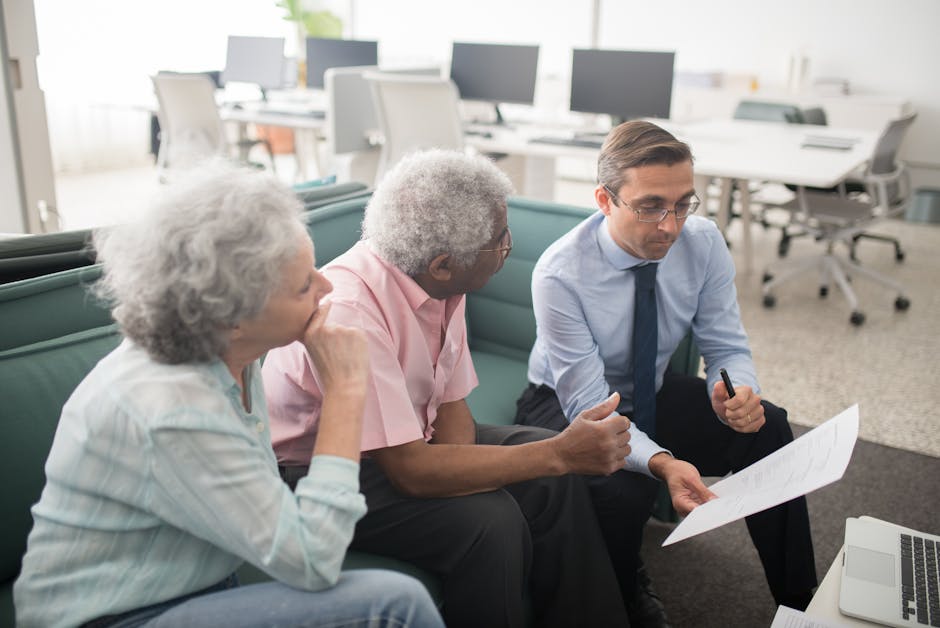
Civil Liability and Consumer Protection: Hidden Legal Risks for Financial Institutions
The legal landscape is shifting, and not in the direction most banks anticipated. Several high-profile civil cases have established that financial institutions can be held liable when they fail to implement reasonable safeguards for elderly account holders. The argument is straightforward: if a bank can flag a $3,000 purchase at an electronics store for fraud review, why can’t it flag a $15,000 wire transfer from an 82-year-old’s account to an unfamiliar recipient?
The answer, according to plaintiff attorneys, is that banks have no financial incentive to scrutinize transactions that generate fees. Until the legal system imposes meaningful consequences, the behavior will not change.
Consumer protection advocates are pushing for mandatory hold periods on large transactions from accounts belonging to seniors over a certain age. The financial industry has pushed back, arguing that such policies would infringe on account holders’ rights and create operational challenges.
Meanwhile, the fraud operations continue to evolve. They now use artificial intelligence to mimic family members’ voices. They create fake Medicare portals that look identical to government websites. They send official-looking documents that reference real Social Security numbers and actual account details.
Similar civil confrontations across the country are forcing community leaders and local venues to confront serious liability under state regulations. Explore the full legal breakdown of related incidents →
Consumer Protection and Financial Fallout: What Precedent Does This Set for Retirement Security?
The precedent being set in courtrooms today will determine whether an entire generation of Americans can trust the systems they spent their lives paying into. Every case that results in a dismissal because the transaction was “authorized” sends a message to fraud operations that the legal system offers no meaningful deterrent.
Elder law attorneys are now recommending that families establish formal power of attorney arrangements before any cognitive decline begins. They advise setting up transaction alerts on all accounts belonging to seniors. They suggest regular family meetings to discuss financial matters openly, removing the stigma that keeps victims silent.
But these are individual solutions to a systemic problem. The families who need protection most are often the ones with the least access to legal resources. The seniors most vulnerable to exploitation are frequently those living alone, without close family oversight, managing their own affairs with fierce independence that predators know exactly how to exploit.

The community dimension of this crisis is what makes it so insidious. When a senior loses their retirement savings, the consequences ripple outward. Adult children reduce work hours to provide care. Local charities absorb the cost of services the senior can no longer afford. The entire community bears the weight of a crime that the legal system often refuses to name.
Some states are now experimenting with mandatory reporting requirements that compel financial advisors to flag suspicious activity. Others are establishing specialized elder fraud units within their attorney general’s offices. The results have been mixed. Reporting requirements without enforcement mechanisms simply create more paperwork. Specialized units without adequate funding cannot handle the volume of cases.
The most promising developments are coming from civil litigation. When a bank is forced to pay damages for failing to protect an elderly customer, other banks notice. When a fraud operation faces a class action lawsuit from multiple victims, the economics of the scheme change.
But these cases take years. They require victims who are willing to endure public scrutiny. They demand attorneys who understand both elder law and financial regulations. And they depend on judges who recognize that “authorized” does not always mean “understood.”
For now, the seniors who lost their retirement savings are left with a brutal reality. The money is gone. The legal system offers no guarantee of recovery. And the operations that took it are already moving on to the next target, refining their methods, exploiting the same gaps in protection that allowed them to succeed the first time.
The question is not whether the system will eventually adapt. It is whether the adaptation will come fast enough to protect the millions of Americans who are approaching retirement age with savings that predators are already planning to take.