The Hidden Financial Trap: How a Routine Tow Can Trigger a Legal and Insurance Nightmare for Ordinary Americans
When private property rules collide with consumer protection laws, the financial fallout lands squarely on the vehicle owner — and most people have no idea what they are legally owed.
Imagine walking to your parking spot after a long shift, only to find an empty space where your car used to be. No note. No warning. Just a missing vehicle and a sinking feeling that this is going to cost you. Within hours, you are staring at a bill that has ballooned from a simple towing charge into hundreds of dollars in storage fees, administrative penalties, and vague “processing” costs that nobody can properly explain.
This is not a rare horror story. It is a daily financial reality for thousands of vehicle owners across the country who suddenly find themselves trapped between private property rules and a confusing web of state and local regulations. The vehicle owner did nothing wrong. Yet they are the one paying the price.
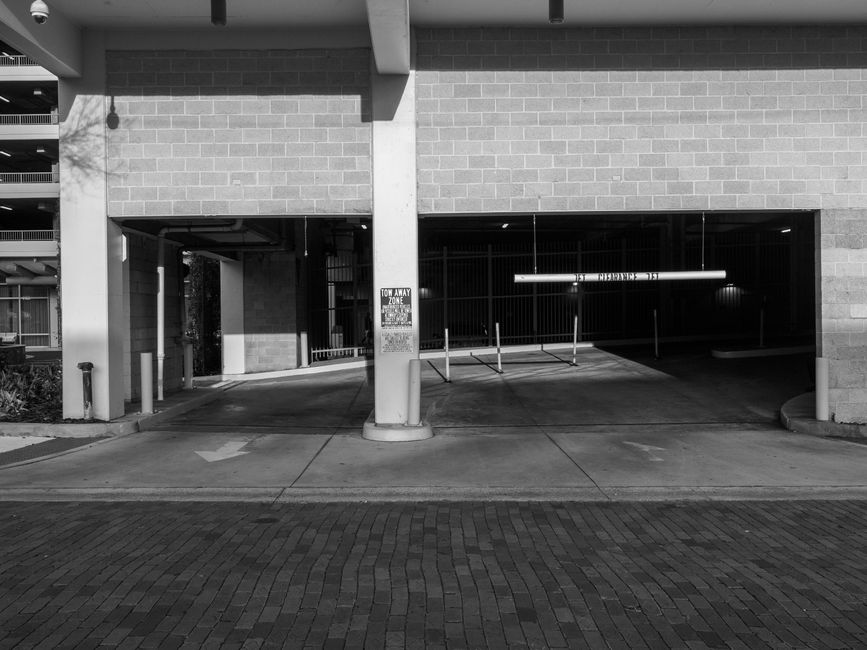
The Legal Precedent: Where Private Rules Clash With State Civil Codes
Here is what most consumers never learn until it is too late. A property owner or their designated towing agent operates under a specific set of legal authorities — but those authorities are not unlimited. State civil codes typically require clear signage, documented authorization, and a defined fee schedule before a vehicle can be legally removed from private property.
When those requirements are skipped, the vehicle owner may have a legitimate legal claim. But proving it requires documentation the average person never thinks to collect in the moment.
“Most people pay the bill because they are scared and exhausted. They never realize they may have been charged illegally from the very first hour.”
The legal standard varies dramatically from state to state. Some states cap the initial tow fee at a fixed dollar amount. Others allow storage fees to begin accruing immediately — sometimes at rates that exceed the daily cost of a rental car. Without knowing your state’s specific consumer protection statutes, you are negotiating blind against a business that does this every single day.
- Did the property owner have valid legal authorization to order the removal, or was it a rogue decision by a single employee?
- Were the posted signs compliant with state civil code requirements, or were they outdated, obscured, or missing entirely?
- Is the storage facility legally permitted to charge daily fees while a consumer dispute is actively pending?
- What documentation is the towing company legally required to provide — and what happens if they refuse?
What makes this situation so financially dangerous is the speed at which costs escalate. A tow that starts at a base rate can multiply within 48 hours. By the time a vehicle owner has gathered the courage and information to challenge the charges, the bill has already tripled.

Civil Liability and Insurance Denials: The Hidden Financial Fallout
Here is where the financial trap truly tightens. Many vehicle owners assume their insurance will cover a towing dispute. It usually will not. Standard auto policies cover accidents, theft, and certain specified perils. They do not cover “administrative” towing disputes, and they certainly do not cover storage fees that accrue while the owner is fighting the charge.
The financial exposure does not stop at the tow bill. If the vehicle was damaged during the removal process, the owner now faces a repair cost that their insurance may classify as a “commercial dispute” rather than a covered claim. This forces the consumer into small claims court — a process that takes months and requires documentation most people never collected.
Meanwhile, the storage facility continues charging daily fees. Some consumers report bills exceeding $1,500 within a single week. For families living paycheck to paycheck, this is not an inconvenience. It is a financial emergency that can trigger debt collection, credit damage, and months of legal wrangling.
Similar civil confrontations across the country are forcing community leaders and local venues to confront serious liability under state regulations. Explore the full legal breakdown of related incidents →
Consumer Protection and Financial Recovery: What Precedent Does This Set?
The legal options available to a consumer in this situation are more powerful than most people realize — but they expire quickly. Most states impose strict deadlines for challenging a tow, often as short as 10 to 15 days from the date of removal. Miss that window, and your legal standing weakens dramatically.
Documentation is everything. Photographs of the parking spot. Copies of any signage. Timestamps of when you discovered the vehicle missing. Written records of every phone call to the towing company and the property owner. These are the pieces of evidence that transform a complaint into a legitimate legal claim.
“The consumer who documents everything and files a formal complaint within the legal window has a fundamentally different outcome than the one who simply pays the bill and moves on.”
State consumer protection divisions and local licensing boards are the two most underused tools available. Filing a formal complaint triggers an investigation that the towing company must respond to. In many cases, companies settle quietly rather than face a licensing review — because their fee structure may not survive scrutiny.

Small claims court remains the most direct path to financial recovery for amounts under the state threshold, which in most jurisdictions ranges from $5,000 to $10,000. The filing fee is modest. The process is designed for people without legal representation. And the burden of proof falls on the towing company to demonstrate that every charge was legally justified.
But here is the part that keeps consumer advocates up at night. The vehicle owner is still without their car. Every day the dispute continues, the storage fees climb. The legal system moves slowly. The towing company’s meter does not.
For the thousands of Americans who will face this exact situation this year, the only real protection is information they did not know they needed. The rules exist. The legal options exist. But they only work for the people who know to use them — and who act before the window closes.