The Hidden Financial Trap: How Private Towing Contracts Are Quietly Draining American Bank Accounts
When a routine morning turns into a four-figure legal dispute, the real question isn’t who was right — it’s who gets stuck with the bill, and why your insurance company may refuse to pay a single cent.
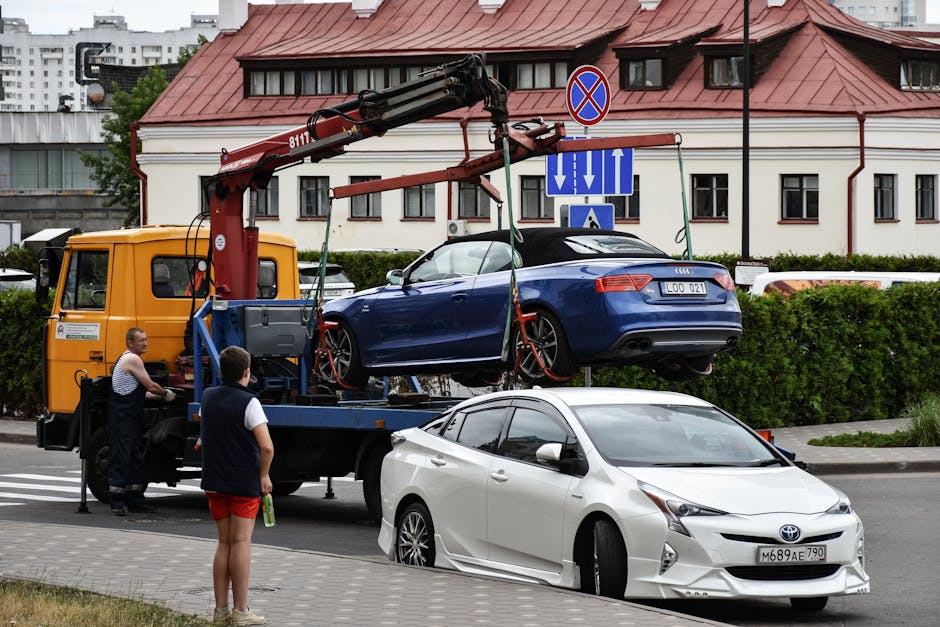
Imagine stepping outside with your morning coffee, only to watch a heavy-duty truck hooking a chain to your family vehicle. No warning. No knock on the door. No explanation. Just a stranger in a reflective vest operating under the color of a private contract you never signed, never read, and almost certainly never agreed to.
That is the reality thousands of American homeowners wake up to every single year. And here is the part nobody tells you at the moment it happens: the financial damage does not stop when the truck drives away.
It starts there. Then it compounds. Then it becomes a legal dispute that can follow you for months.
The Legal Precedent: Where Private Rules Clash With State Civil Codes
Most Americans assume that if a tow happens on their property, they have automatic legal standing to dispute it. That assumption is dangerously wrong.
Private towing operations frequently act under agreements signed with property management companies, homeowners associations, or commercial landlords — entities that hold contractual authority the individual resident often has zero visibility into. That contract, buried in a lease appendix or an HOA bylaws packet, can grant sweeping authority to remove vehicles with minimal notice.
The legal question that follows is not simply “was the tow justified.” It is whether the private contract itself complies with state civil codes governing property removal, notification requirements, and consumer protection statutes.
That is the leverage most consumers never use. They pay the fee. They retrieve the car. They move on. And the operator keeps the profit.
- Did the property management company properly disclose the towing contract to the resident in writing?
- Was the required advance notice period under state civil code actually observed before removal?
- Can the vehicle owner recover storage fees, lost wages, and statutory damages through a wrongful conversion claim?
- Will the insurance carrier deny the claim based on a “commercial removal” exclusion buried in the policy fine print?
Civil Liability & Insurance Denials: The Hidden Financial Fallout
Here is where the story turns genuinely ugly for the average American family.
You file a claim with your auto insurance carrier. You assume they will cover the towing fee, the storage charges, and any damage incurred during removal. Then the denial letter arrives.
Insurance policies routinely exclude losses arising from “commercial or contractual removal” of a vehicle. That single line of policy language has wiped out tens of thousands of dollars in consumer claims across the country. The carrier is not obligated to pay a fee it classifies as a third-party contractual charge — even when the policyholder had no say in the contract.
“The consumer is caught between two contracts they never negotiated — the property agreement and the insurance policy — and both are written to protect the other party.”
Storage fees, meanwhile, do not pause. They accumulate daily. In some jurisdictions, operators can file for a mechanic’s lien or initiate a title transfer after a set number of days. That means a $250 tow can snowball into a $3,000 financial liability in under three weeks.
Similar civil disputes across the country are forcing homeowners and local venues to confront serious liability under state consumer protection regulations. Explore the full legal breakdown of related incidents →
Consumer Protection & Financial Recovery: What Precedent Does This Set?
The most important question is not what happened in one driveway. It is what happens in the next thousand.
Consumer protection attorneys argue that the current framework heavily favors the operator. Notification requirements vary wildly by state. Some jurisdictions require a phone call. Some require a written notice posted 24 hours in advance. Some require nothing at all if the property agreement contains a blanket removal clause.
That patchwork of rules is precisely why financial recovery is so difficult. A consumer who does not know their state’s specific statutory requirements cannot effectively challenge the charge — and the operator knows it.
What does work, according to consumer rights advocates, is documentation. Photographs of the scene. Timestamps. A copy of the lease or HOA agreement. Written demand letters citing the specific state civil code section. And in many cases, a small claims filing that costs under $100 but forces the operator to justify the charge in front of a judge.
The math is brutal for the operator. Defending a $400 tow in court often costs more than the tow itself. That is the leverage the consumer holds — if they know it exists.
Meanwhile, the broader financial exposure keeps growing. Insurance carriers are tightening exclusions. Property managers are signing broader removal authority into leases. And the storage yards keep filling up with vehicles whose owners are quietly deciding whether it is cheaper to pay or to fight.
Most pay. That is the business model.
But the ones who fight are discovering something the industry would prefer stayed buried: state civil codes often side with the consumer when the paperwork is not perfect. And the paperwork is almost never perfect.
The next truck that pulls into a driveway will not announce whether the contract behind it is enforceable. The homeowner will have to figure that out. Usually alone. Usually after the fees have already started stacking.