The Quiet Erosion of Senior Financial Independence: Inside the Fight to Shield Retirement Savings From Modern Exploitation
As elder fraud schemes grow more sophisticated, families across the country are discovering that the battle for senior financial protection is being fought at kitchen tables, bank counters, and probate courts
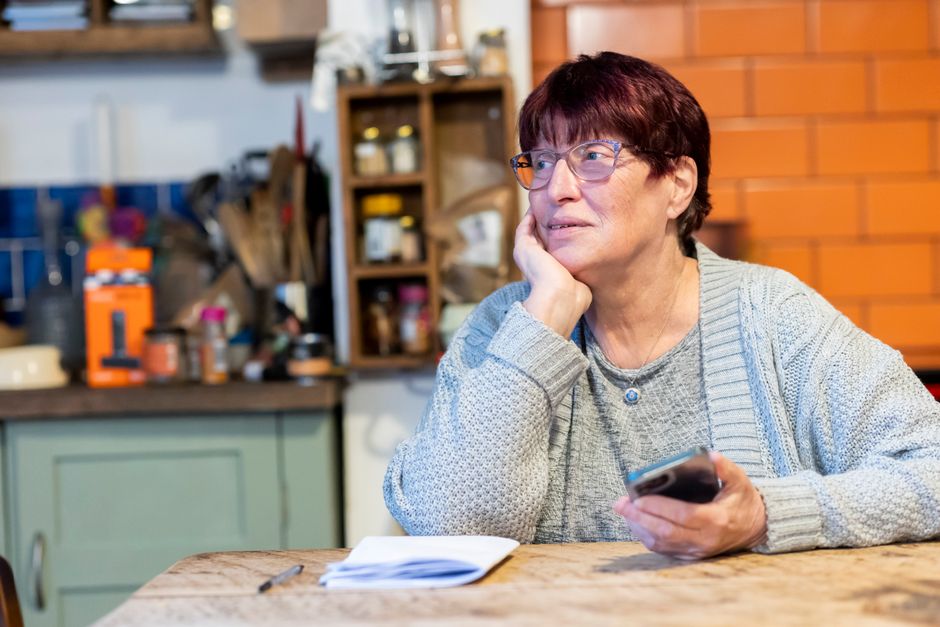
An 82-year-old widow sits at her kitchen table, staring at a bank statement she does not recognize. The balance is wrong. The transfers are wrong. And the person who was supposed to protect her is the one who signed off on every single one. This is not a rare horror story. This is the new American reality of elder financial exploitation, and it is happening in broad daylight, with paperwork, not ski masks.
The numbers are staggering. Federal authorities estimate that older Americans lose tens of billions of dollars every year to schemes ranging from fake Medicare billing to so-called “grandparent” phone scams to quiet, methodical theft by the very relatives and caregivers entrusted with their care. The money disappears. The dignity disappears. And too often, the family only finds out after the estate is already hollowed out.
What makes this crisis so devastating is that it rarely looks like a crime in progress. It looks like a son helping mom with her bills. It looks like a “trusted” financial advisor offering a better return. It looks like a Medicare call center confirming a “routine” equipment order that was never requested. By the time the family connects the dots, the legal clock has already started ticking.
“Elder financial exploitation is one of the fastest-growing categories of fraud in the country, and the victims are often the least equipped to recover what was taken.”
The Legal Precedent: Where Power of Attorney Clashes With State Elder Protection Statutes
Here is where the legal machinery gets complicated. Every state has its own elder protection statutes, its own Adult Protective Services framework, and its own rules about when a power of attorney document becomes a weapon instead of a shield. A durable power of attorney, signed in good faith decades ago, can be the single most dangerous piece of paper in a senior’s file if the agent named in it decides to go rogue.
Family attorneys describe a recurring nightmare scenario: an aging parent grants power of attorney to one adult child, the other siblings find out years later, and by then the accounts have been drained, the house has been refinanced, and the beneficiary designations have been quietly rewritten. Probate litigation follows. Families fracture. And the senior, often in cognitive decline, is caught in the middle of a legal war they never saw coming.

- When does a power of attorney cross the line from legitimate management into actionable elder financial exploitation under state law?
- What civil liability exposure do banks, financial advisors, and Medicare billing contractors face when they fail to flag suspicious account activity on senior accounts?
- How aggressively are state Adult Protective Services agencies actually pursuing financial exploitation cases compared to physical neglect complaints?
Civil Liability and Business Codes: Hidden Legal Risks for Financial Institutions and Care Providers
The institutions are not off the hook. Under a growing patchwork of state consumer protection statutes and federal banking regulations, financial institutions have an affirmative duty to detect and report suspected elder financial exploitation. When they fail, the legal exposure can be enormous. Attorneys general in multiple states have pursued civil enforcement actions against banks, annuity sellers, and Medicare billing intermediaries that looked the other way while senior accounts were drained.
Medicare fraud is its own beast. The program loses an estimated tens of billions annually to fraudulent billing, phantom equipment orders, and kickback schemes targeting seniors who simply do not know how to verify what was billed in their name. Seniors are frequently told they owe nothing, so they do not question the paperwork. Meanwhile, their Medicare number is being used as a billing engine for criminal enterprises.
“The senior rarely sees the bill. The senior rarely sees the fraud. That is exactly the point.”
Similar civil confrontations across the country are forcing community leaders and local venues to confront serious liability under state regulations. Explore the full legal breakdown of related incidents →

Consumer Protection and Financial Fallout: What Precedent Does This Set for Retirement Security?
The fallout extends far beyond any single victim. When a senior’s retirement savings are wiped out, the burden shifts to the family, to Medicaid, and ultimately to taxpayers. Retirement security is not just a personal issue. It is a public policy issue, and the legal precedent being set right now in state courts across the country will determine how aggressively future exploitation cases are prosecuted.
Estate attorneys advise families to take three basic steps immediately: request a credit freeze on the senior’s accounts, review every power of attorney and beneficiary designation document, and set up third-party monitoring of all financial accounts. The families that do this catch exploitation early. The families that do not often discover the damage at the reading of the will.
The schemes keep evolving. The legal system keeps scrambling to catch up. And somewhere right now, at a kitchen table in a quiet American suburb, an 82-year-old widow is staring at a bank statement she does not understand, wondering why the phone keeps ringing, and wondering who she can still trust.