The Hidden Financial Trap: What a Routine Retail Dispute Reveals About Your Legal Rights and Liability
When a simple transaction turns into a public accusation, the financial fallout can be devastating. Here is what ordinary Americans rarely understand about their legal options and the true cost of a dispute.
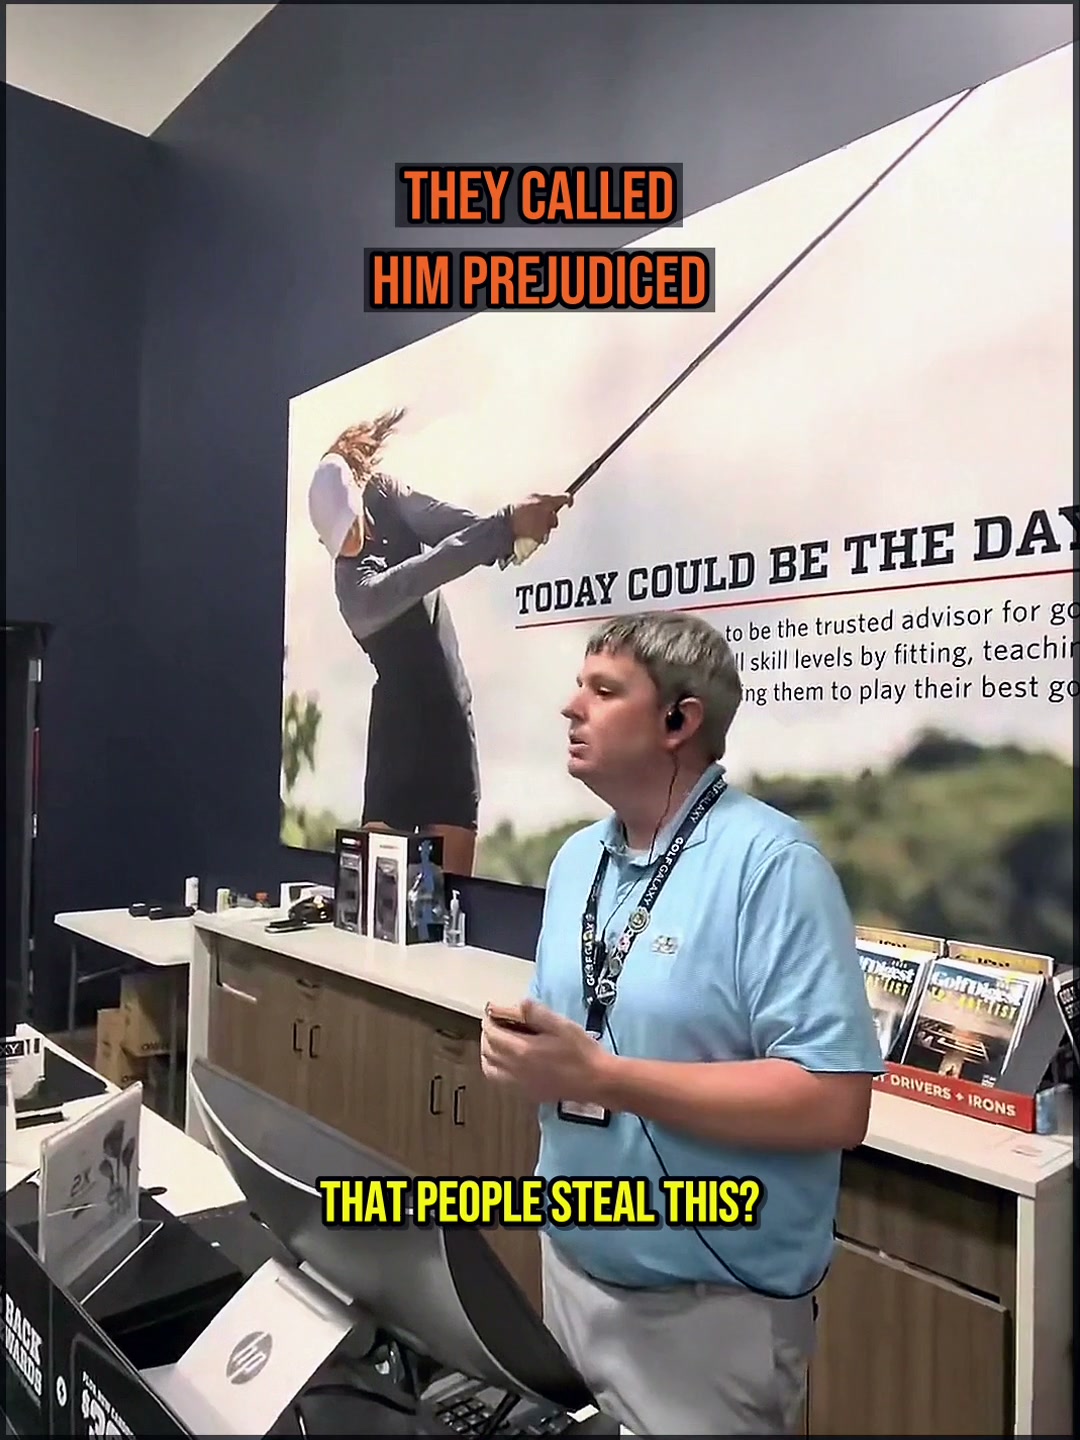
Imagine walking into a retail store to make a simple purchase, only to find yourself at the center of a public accusation that threatens your reputation and your wallet. For one couple, a trip to a local golf retailer turned into a financial and emotional nightmare that exposes a terrifying gap in consumer protection. The incident, captured on video, shows the couple demanding accountability from a cashier, but the real story is the hidden financial liability that could affect any American shopper.
According to public records and witness observations, the dispute erupted when the couple alleged discriminatory treatment during a transaction. The cashier, caught off guard, attempted to de-escalate, but the confrontation quickly drew attention from other customers. What started as a routine purchase became a masterclass in how quickly a civil dispute can spiral into legal and financial chaos.
The couple’s demand for accountability raises a critical question: what legal options do ordinary Americans have when they believe they have been wronged in a retail setting? Most people assume that a verbal accusation is harmless. They are wrong. Under state civil codes, a public accusation can trigger defamation claims, emotional distress lawsuits, and even consumer protection violations. The financial stakes are enormous.
“The moment you are publicly accused in a retail environment, your legal exposure begins. Most people do not realize they can be sued for defamation even if the accusation is verbal and unrecorded.”
For the cashier, the financial liability is equally terrifying. If an employer fails to protect an employee from a hostile customer interaction, the business could face workers’ compensation claims and civil liability. The cashier becomes a pawn in a larger legal battle that neither party fully understands.
The Legal Precedent: Where Private Rules Clash With State Civil Codes
Retail stores operate under a complex web of private policies and state civil codes. When a dispute occurs, the store’s internal rules often conflict with consumer protection laws. For example, a store may claim the right to refuse service, but state civil codes may prohibit discriminatory refusal. This legal gray area is where financial liability explodes.
Legal experts point out that most Americans do not know their rights in these situations. They do not know they can request a corporate investigation, file a consumer protection complaint, or seek legal recourse for emotional distress. The result is a financial trap: the victim of a dispute often ends up paying legal fees while the business hides behind liability insurance.

- Does a verbal accusation in a retail setting constitute defamation under state law?
- Can the cashier sue the customer for emotional distress, or is the employer liable?
- What financial damages can be recovered when no physical injury occurs?
- Do standard homeowners or renters insurance policies cover defamation claims?
The financial stakes are not limited to the immediate parties. Retail businesses face rising insurance premiums, legal defense costs, and potential settlements. These costs are passed on to consumers through higher prices. The couple’s public dispute is a microcosm of a national problem: the lack of financial literacy regarding legal liability.
Civil Liability & Business Codes: Hidden Legal Risks for Local Venues
Local venues and retail stores are bound by business codes that mandate a safe environment for both customers and employees. When a dispute escalates, the business can be held liable for failing to intervene, failing to train employees, or failing to document the incident properly. These are not abstract legal theories. They are financial realities that can bankrupt a small business.
For the couple, the financial fallout could include lost wages from time spent dealing with the incident, legal consultation fees, and potential counterclaims from the store. For the cashier, the risk of termination and the inability to find future employment in the retail sector is a real financial threat. Neither party has the resources to navigate this alone.
“The average American has less than $1,000 in savings. A single legal dispute can wipe out that cushion in a matter of days. This is not a moral issue. It is a financial crisis waiting to happen.”
Consumer protection agencies report a surge in complaints related to retail disputes, but most cases never reach a courtroom because the financial cost of litigation is prohibitive. The couple in this incident may never see justice, not because they are wrong, but because they cannot afford the fight. This is the hidden injustice that no one talks about.
Similar civil confrontations across the country are forcing community leaders and local venues to confront serious liability under state regulations. Explore the full legal breakdown of related incidents →
Consumer Protection & Financial Fallout: What Precedent Does This Set?
The precedent set by cases like this one is chilling. It tells businesses that they can hide behind liability insurance and legal teams while ordinary consumers are left to fend for themselves. It tells consumers that their rights are only as strong as their bank account. This is not a recipe for justice. It is a recipe for financial inequality.
Legal options exist, but they are not widely known. Consumers can file complaints with state attorneys general, seek mediation through consumer protection agencies, and in some cases, pursue small claims court actions. However, these options require time, money, and legal knowledge that most Americans do not have.

The financial accountability in this case is not just about who pays. It is about who is protected. The couple’s demand for accountability is a demand for a system that works for everyone, not just those who can afford it. The cashier’s silence is a reminder that ordinary workers are often the first to pay the price when systems fail.
What happens next is uncertain. The store may settle quietly. The couple may pursue legal action. The cashier may lose their job. But one thing is certain: the financial and legal fallout will continue long after the cameras stop rolling. The real question is whether anyone will learn the truth about their rights before it is too late.
The unedited truth is that most Americans are one dispute away from financial ruin. They do not know their rights. They do not have liability coverage. They do not have legal representation. And the system is not designed to help them. It is designed to protect those who can afford to protect themselves. Until that changes, incidents like this will keep happening, and the financial consequences will keep piling up.