The $5,000 Promise: Why That Check May Never Clear Your Bank Account
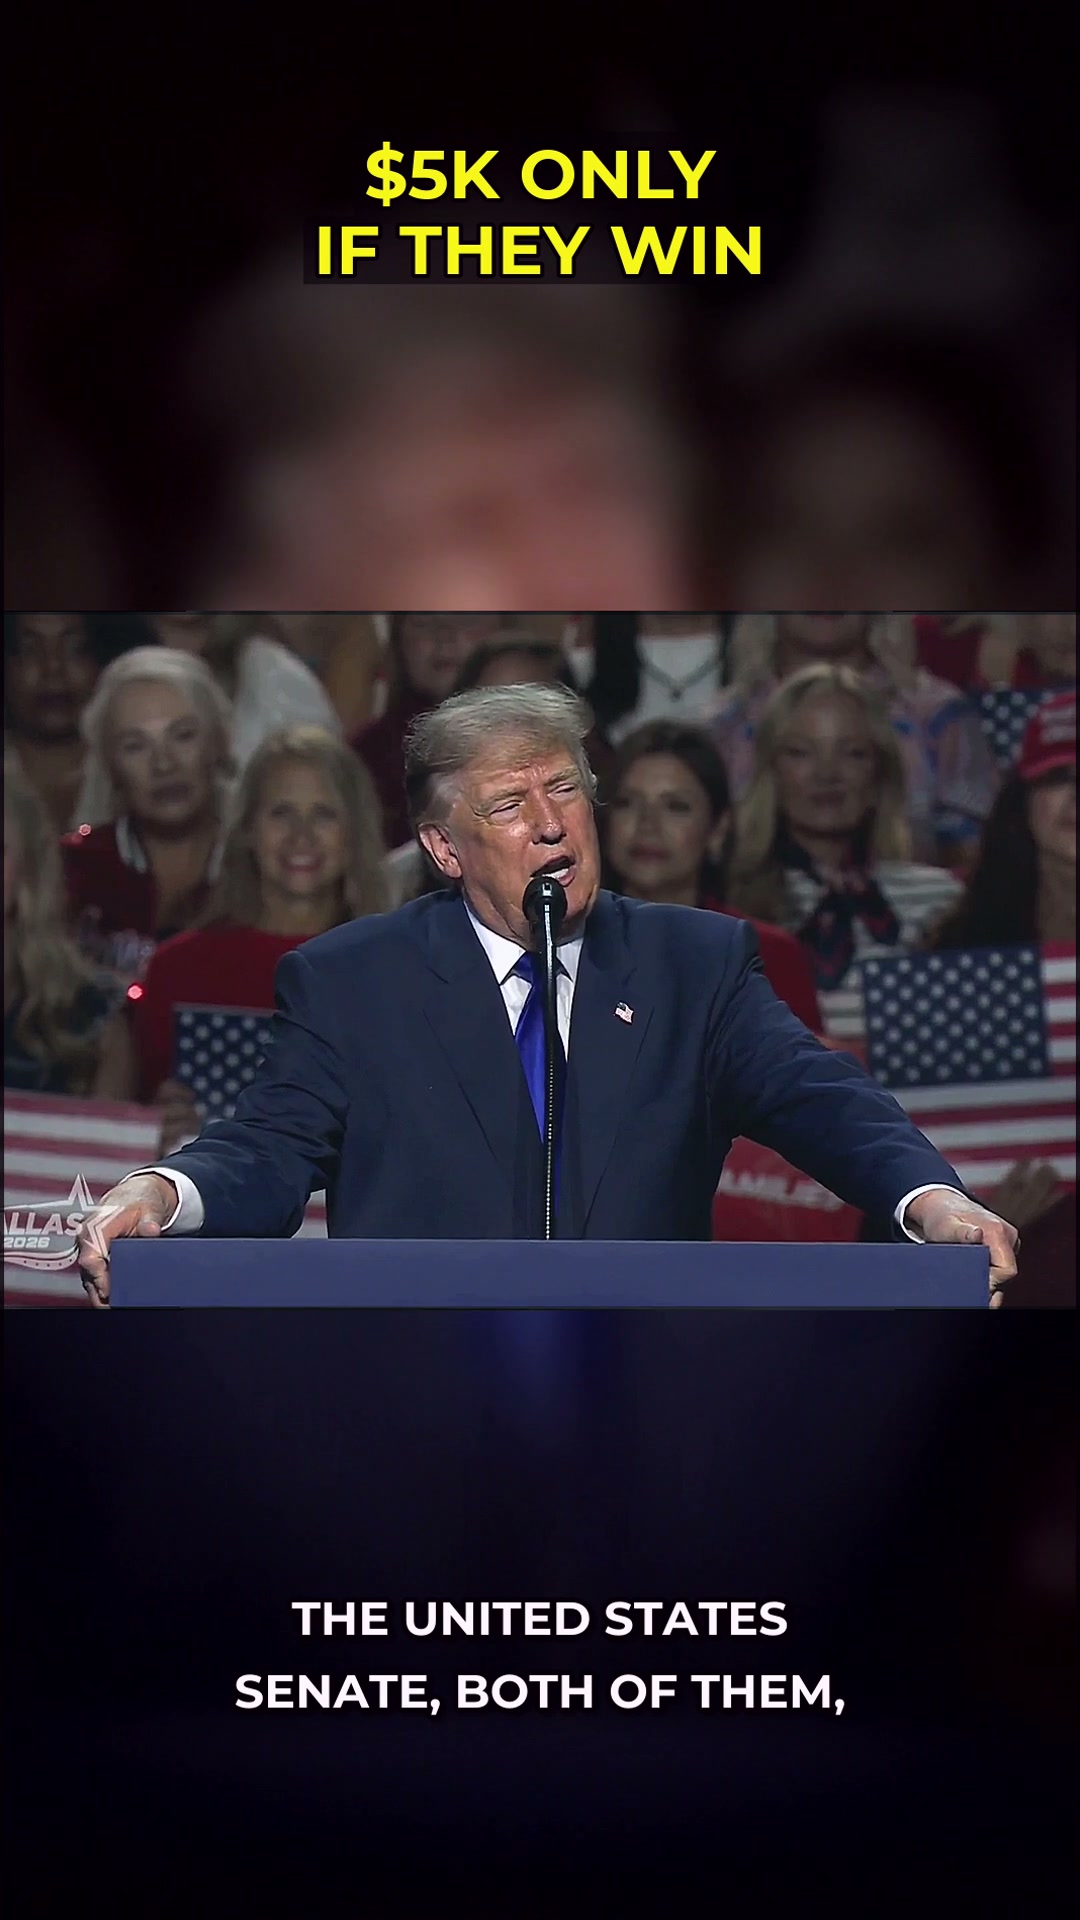
A headline-grabbing dividend announcement is reigniting a national debate, but the financial and legal fine print tells a far more complicated story for ordinary households.
- A proposed $5,000 payment is being framed as a shareholder-style dividend.
- No legislation, funding mechanism, or disbursement timeline has been confirmed.
- Americans should understand how unverified windfalls affect taxes, debt, and credit.
Imagine refreshing your bank app on a Tuesday morning and seeing an extra five thousand dollars sitting in your checking account. That is the fantasy being sold right now. The problem is that fantasies do not pay rent, and they do not survive contact with the fine print.
The announcement in question frames a massive cash payment to every adult citizen as something similar to a company issuing cash distributions to its shareholders. It is a compelling pitch. It is also not a law, not a budget line, and not a check in the mail.
The Shareholder Analogy Falls Apart Fast
Companies pay dividends out of profits. They do it after accountants, auditors, and boards sign off on the numbers. If a company promises money it does not have, shareholders sue. Executives face legal exposure. There are consequences.
Governments do not operate like that. A federal payment to every adult would require congressional authorization, a funding source, and an administrative apparatus to actually move the money. None of that has been confirmed.
“If the Republicans win the House of Representatives and the United States Senate, both of them, because of our economic, tremendous economic success, like in history we’ve never had anything like what’s happening.”
That is the entire condition. Win two chambers, and the money flows. It sounds simple. It is not.
What This Means For Your Actual Finances
Here is where it gets dangerous. When headlines promise free money, people make real decisions. They delay debt payments. They skip insurance premiums. They take on new obligations because help is supposedly coming.
That is a financial trap. Credit card interest does not pause for political announcements. Utility shutoff notices do not care about campaign rhetoric. Landlords do not accept promises as payment.

If a payment like this ever materialized, it would almost certainly be taxable income. That means a chunk of it could be owed back to the Internal Revenue Service the following April. Many Americans learned this lesson the hard way with state stimulus payments that arrived with no withholding.
There is also the debt collection angle. A sudden deposit into a bank account can be seized by creditors holding a valid judgment. Without proper planning, a windfall can vanish before the recipient ever touches it.
“Only I can make this promise to you.”
That line is doing enormous work. It positions the payment as personal, exclusive, and guaranteed by one individual. Legally, it means nothing. Practically, it means everything to a voter who is struggling.
The Legal Precedent Nobody Is Talking About
Courts have consistently held that campaign promises are political speech, not enforceable contracts. A candidate who vows to build a wall, cut taxes, or send checks is not legally bound to deliver. Voters cannot sue for breach of promise.
This matters because the gap between announcement and enactment is where ordinary people get hurt. They budget around a payment that never arrives. They sign leases, finance cars, and swipe credit cards based on a headline.
Consumer protection attorneys see this pattern constantly. Predatory lenders and scam operators weaponize anticipation. Fake government grant offers, advance-fee schemes, and phishing texts all explode during periods of high-profile financial announcements.
What You Should Actually Do Right Now
Ignore the number. Focus on your own ledger. Pay down high-interest debt. Keep an emergency fund. Document every financial decision you make over the next year.
If a real payment ever passes Congress and gets signed into law, you will know. It will have a disbursement date, a tax treatment, and an official government website. Until then, treat every dollar you have as if it is the only dollar coming.
Because for most Americans, it is.