The Richmond Jewellery Heist: Who Foots the Bill When Luxury Vanishes in Broad Daylight?
A brazen morning robbery exposes the brutal fine print of insurance policies and the legal maze victims face when their most valuable assets disappear.
- Insurance companies routinely deny high-value jewellery claims over technicalities like missing appraisals or security system failures.
- Victims of theft have specific legal options to challenge denials, including filing complaints with financial ombudsman services.
- Documentation and immediate reporting are not just procedural steps—they are the legal foundation for any recovery attempt.
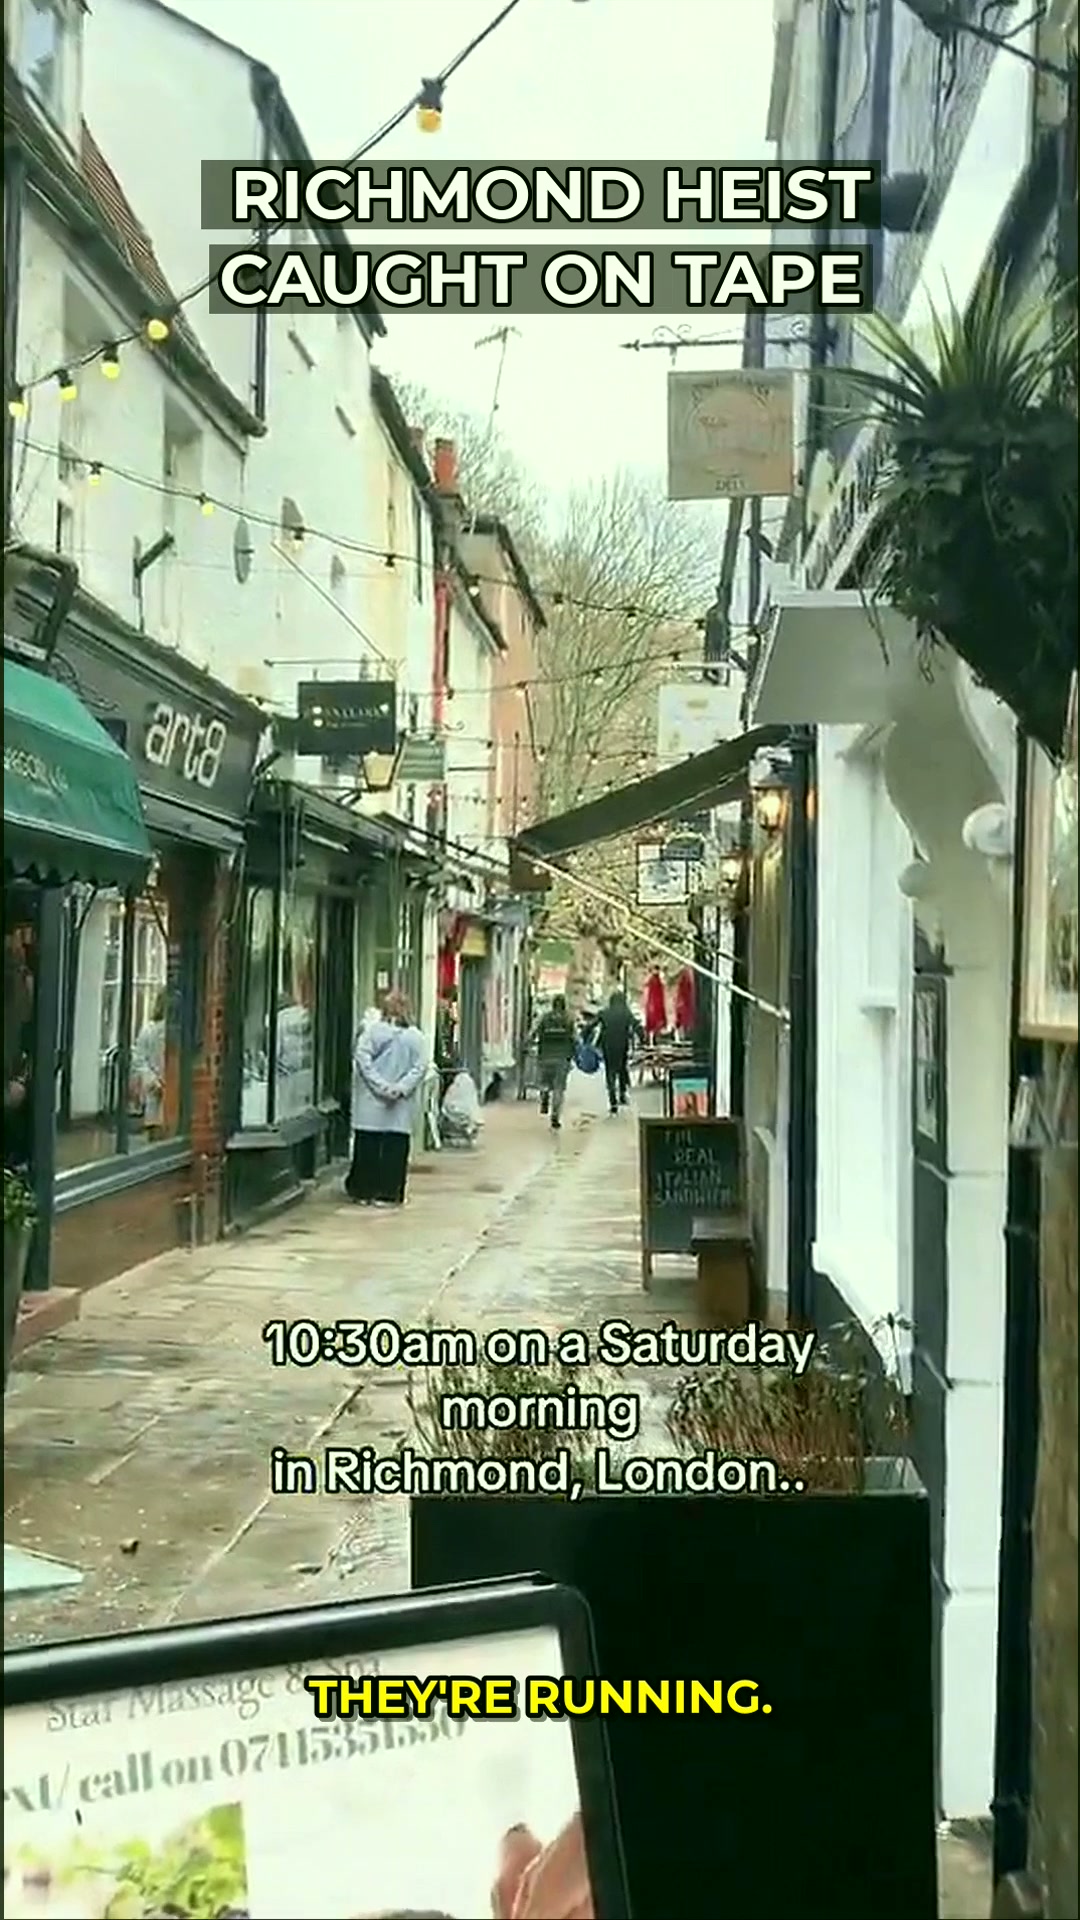
Imagine standing on a quiet Richmond street, the morning still crisp, when suddenly a group of individuals bolts past you—arms full of stolen luxury goods, hearts pounding, and zero hesitation. That was the scene this morning as a jewellery robbery unfolded in plain sight, leaving witnesses stunned and local shop owners scrambling to process what they had just seen.
The footage captures the chaos: onlookers gasping, pointing, and noting that the suspects veered left towards the green. But the most chilling observation from a bystander? “No one’s got the arms here.” No security. No immediate intervention. Just a brazen getaway and a trail of financial destruction left behind.

The Financial Wreckage No One Talks About
While the physical theft is over in seconds, the financial aftermath for the business owner is just beginning—and it is far uglier than most people realize. High-value jewellery inventory represents not just stock, but often a lifetime of savings, loans, and reinvested profits. When that inventory walks out the door, the owner is left staring at a ledger that suddenly bleeds red.
Here is the uncomfortable truth that insurance companies do not advertise: standard business insurance policies often exclude “mysterious disappearance” or require specific security measures—like armed guards or reinforced safes—that many small shops simply cannot afford. The moment a claim is filed, adjusters will scour the policy for any technicality to reduce the payout.
This is not about a lack of sympathy from insurers. It is about a cold, calculated system designed to protect their bottom line. The victim is not just robbed once on the street—they are robbed again in the claims office.
“No one’s got the arms here. That’s the problem.” — A witness at the scene, capturing the terrifying lack of deterrent that emboldens criminals.
The Legal Precedent: What Victims Can Actually Do
Under UK law, a business owner who suffers a robbery has a legal pathway that extends far beyond filing a police report. The Theft Act 1968 defines the crime, but the real battleground is civil recovery. If the suspects are caught and convicted, a victim can pursue a compensation order through the criminal courts. If they are not caught—which is common in fast-moving street robberies—the focus shifts entirely to the insurance contract.
Here is where most victims stumble: they accept the first settlement offer. They do not realize that they have the right to challenge a denial or lowball offer through the Financial Ombudsman Service, a free and independent body that rules on disputes between consumers and financial firms. In many cases, the mere threat of an ombudsman complaint forces insurers to revisit their position.
But there is a catch. The ombudsman will only side with the policyholder if the business can prove it met every condition in the policy. This means having up-to-date appraisals, CCTV footage that actually works, and a log of security checks. Without this documentation, the legal options shrink dramatically.
The harsh reality is that accountability cuts both ways. The criminals are accountable to the law, but the insurance company is accountable only to the fine print. And the business owner? They are accountable for every single detail—whether they knew it or not.

The Uncomfortable Question No One Wants to Ask
As the suspects disappeared towards the green, leaving witnesses in shock, a deeper concern lingers for every shop owner watching this unfold: Is my business next? And if it is, will my insurance actually protect me, or will I be left fighting a bureaucratic machine while my livelihood crumbles?
The witnesses on the street were right about one thing—there was no visible security presence. But the real vulnerability is not the lack of guards at that exact moment. It is the lack of legal preparation long before the criminals ever walked through the door.
Every jewellery store owner in Richmond—and every city across the UK—should be reviewing their policy today. Not tomorrow. Not after the next incident. Because the moment a robbery happens, the clock starts ticking not just on the investigation, but on the window to file a claim that will actually be honoured.
The suspects may have vanished this morning, but the consequences of their actions are just beginning to surface. And for the victim, the fight is only the opening scene of a long, expensive legal battle.